Florida Hurricane Season: Is Your Home Insurance Ready?
Janina Ramirez-Fagan
Home & Property Coverage Specialist
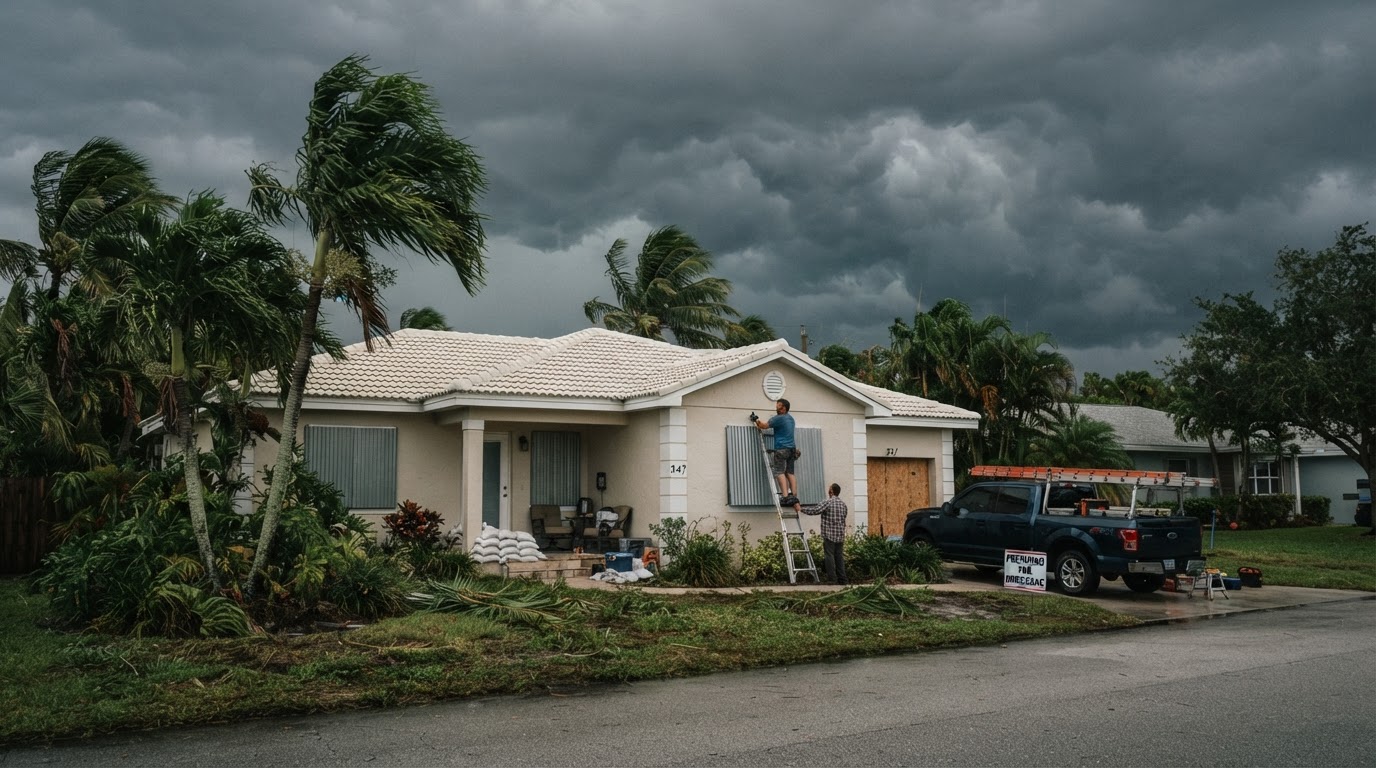
Florida's hurricane season runs June 1 through November 30, and the Sunshine State leads the nation in hurricane-related insurance claims. Yet many homeowners discover too late that their policy doesn't cover what they assumed it would. Here's how to audit your coverage before the next storm — not after.
Wind vs. Flood: The Coverage Gap That Costs Homeowners
This is the single most misunderstood part of Florida home insurance. Standard homeowners insurance covers wind and hurricane damage, but it does NOT cover flooding — not even flooding caused by a hurricane.
- Wind/Hurricane damage (roof torn off, windows blown in) → covered by your homeowners policy, subject to your hurricane deductible.
- Flood damage (storm surge, rising water) → only covered by a separate flood insurance policy.
Did you know?
More than 20% of flood claims come from properties outside of mapped high-risk flood zones. If you live anywhere in Florida, flood insurance is worth a serious look — there's typically a 30-day waiting period before coverage takes effect.
Understanding Your Hurricane Deductible
Florida policies usually carry two deductibles: a standard "all other perils" deductible and a separate, higher hurricane deductible. Hurricane deductibles are typically calculated as a percentage of your home's insured value (commonly 2%, 5%, or 10%) — not a flat dollar amount.
On a $400,000 home with a 5% hurricane deductible, you'd pay the first $20,000 out of pocket after a named-storm claim. Knowing this number before storm season lets you set aside funds or adjust your deductible to better fit your budget.
The 6-Point Hurricane Insurance Checklist
- Confirm your dwelling limit reflects today's rebuild cost — construction prices in Florida have risen sharply.
- Check your roof's age and replacement schedule — some carriers limit or exclude coverage on roofs over 15–20 years old.
- Review your hurricane deductible and make sure you could cover it if a storm hits.
- Verify loss of use / additional living expenses coverage in case you're displaced.
- Get a flood insurance quote even if you're not in a high-risk zone.
- Document your belongings with a video walkthrough and receipts stored in the cloud.
What About Wind Mitigation Credits?
Florida rewards homes built or upgraded to resist wind damage. Features like a hip roof, hurricane straps, impact-rated windows, and a secondary water resistance barrier can qualify you for wind mitigation discounts that meaningfully lower your premium. If you've never had a wind mitigation inspection, it's one of the fastest ways to reduce your cost without reducing coverage.
Should You Add an Umbrella Policy?
After a major storm, liability risks rise — fallen trees on a neighbor's property, contractor disputes, or someone injured on your damaged property. An umbrella policy adds $1 million+ of liability protection for a few hundred dollars a year and is one of the highest-value coverages a Florida homeowner can carry.
The Bottom Line
Hurricane readiness isn't just about shutters and supplies — it's about knowing exactly what your policy will and won't pay for. A 15-minute policy review with an independent agent can reveal gaps that would otherwise cost tens of thousands after a storm.
Our Tampa Bay team will review your current home policy, explain your hurricane deductible in plain English, and show you quotes from multiple carriers — at no cost to you. Get a free home insurance quote or re-shop your current policy today.